SEIS / EIS
SEIS and EIS for Software and SaaS Companies: A Practical UK Guide
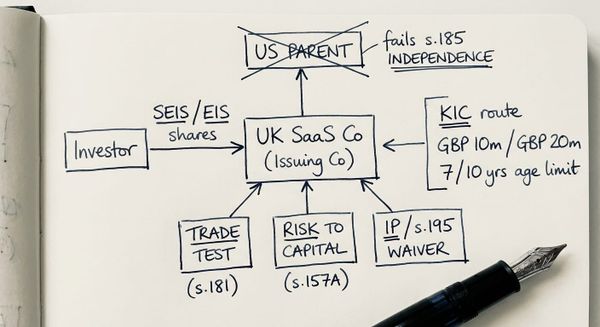
How SEIS and EIS apply to UK software and SaaS companies. Trade tests, risk to capital, IP traps and KIC status. Steve Livingston FCA, IP Tax Solutions.
Steve Livingston LLB FCA is the Founder of IP Tax Solutions. Having trained at Big 4 firm, KPMG, and progressed to Senior Manager, he was appointed as a Partner at a mid-tier global firm.
SEIS / EIS
How SEIS and EIS apply to UK software and SaaS companies. Trade tests, risk to capital, IP traps and KIC status. Steve Livingston FCA, IP Tax Solutions.
SEIS / EIS
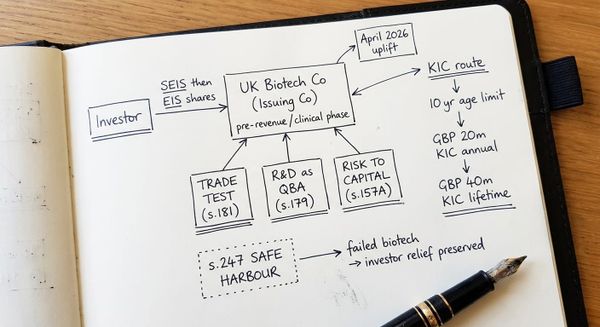
How SEIS and EIS apply to UK loss-making biotech. Trade test, R&D as qualifying activity, KIC status, April 2026 EIS uplift and loss relief on failure.
Enterprise Management Incentives
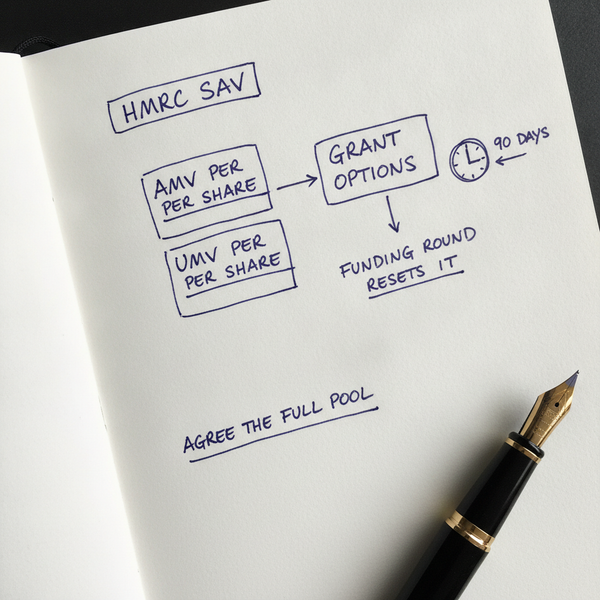
EMI share valuation explained: what HMRC's Shares and Assets Valuation team checks, why valuations get challenged and how to get agreement first time.
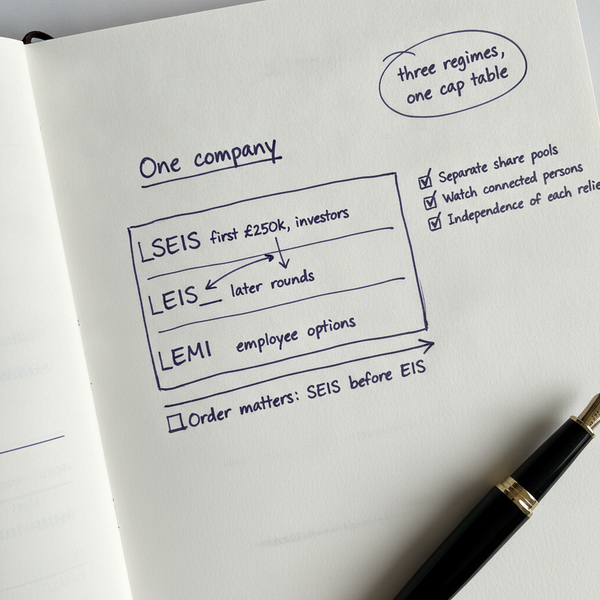
Enterprise Management Incentives
A company can use SEIS, EIS and EMI together. Learn how to sequence the EMI grant around your funding round to protect investor relief and option value.
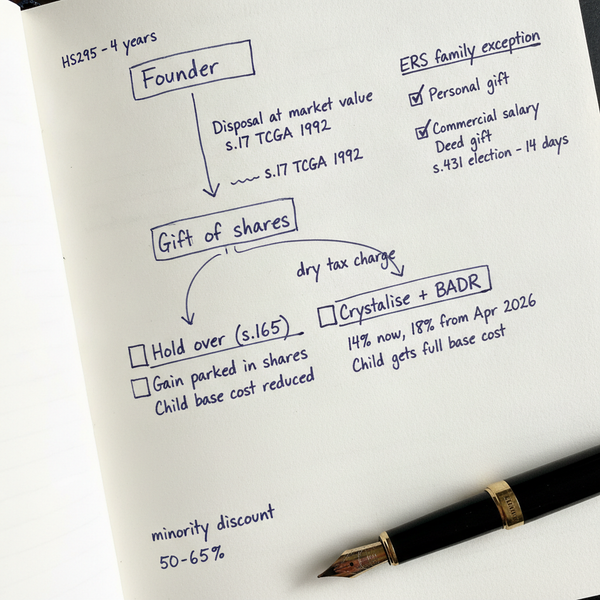
Founder Equity Tax
Transferring shares to your children triggers CGT at market value. How s.165 holdover relief, the ERS family exception and BADR apply to a family gift.
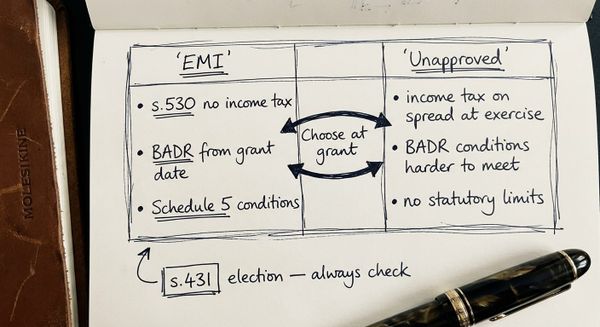
Enterprise Management Incentives
EMI options and unapproved share options both incentivise key people. Understand the tax treatment, when each is right, and where each breaks down.
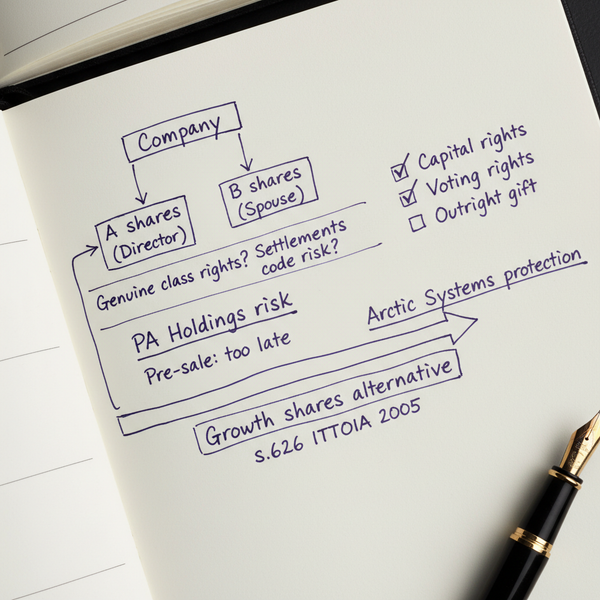
Alphabet shares look like a simple income-splitting tool. Here is why HMRC challenges them, when Arctic Systems protects you, and what to use instead.
Enterprise Management Incentives
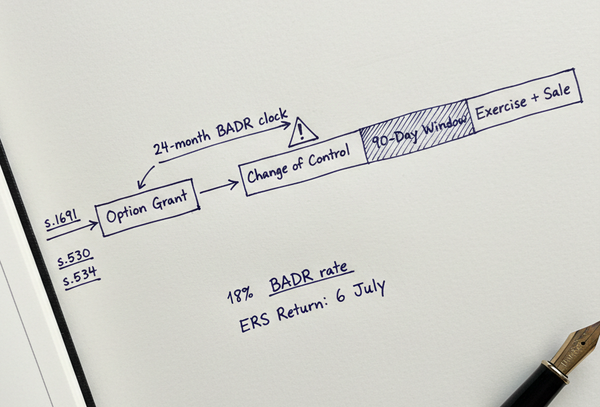
When your company is sold, EMI option holders face key decisions on timing, BADR eligibility and ERS filing. Steve Livingston FCA explains the framework.
Enterprise Management Incentives
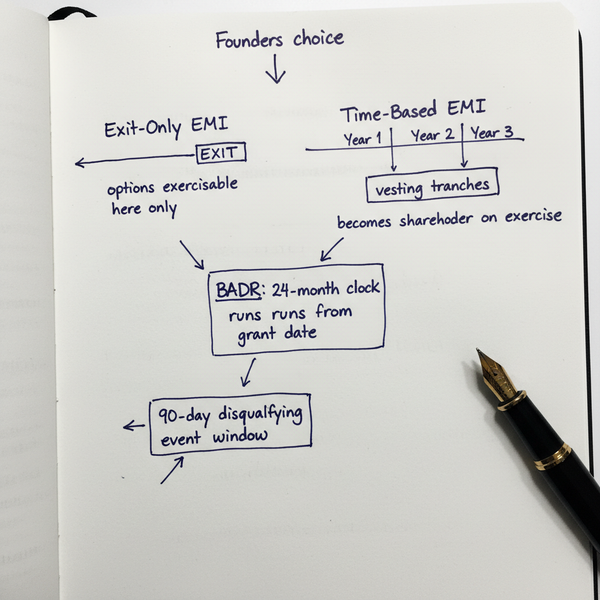
Should your EMI scheme be exit-only or time-based? Steve Livingston LLB FCA explains the strategic choice, BADR implications and the disqualifying event trap.
Enterprise Management Incentives
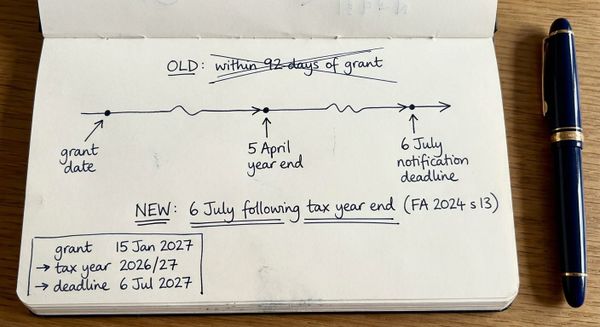
For EMI options granted on or after 6 April 2024, the notification deadline is 6 July following the tax year end. Here is what changed and how to comply.
Enterprise Management Incentives
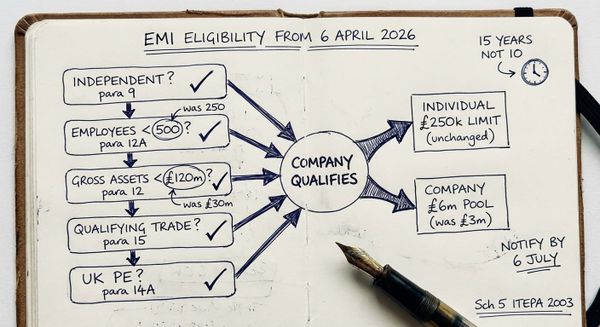
New 500-employee and £120m gross asset limits took effect on 6 April 2026. Find out whether your company now qualifies for EMI options and what to do next.
R&D Tax Credits
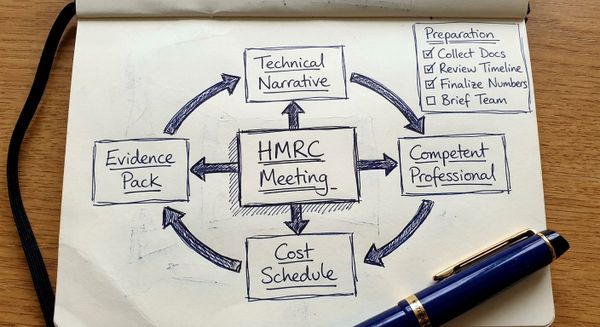
HMRC has requested a meeting about your R&D claim. Learn what to expect, what to bring, and how to avoid the mistakes that cost companies their credits.