Unapproved Share Options for Advisers and Consultants: How Are They Taxed?
How unapproved options for advisers and consultants are taxed in the UK: when ERS applies, grant and exercise charges, VAT, SEIS and EIS effects and a grant checklist.
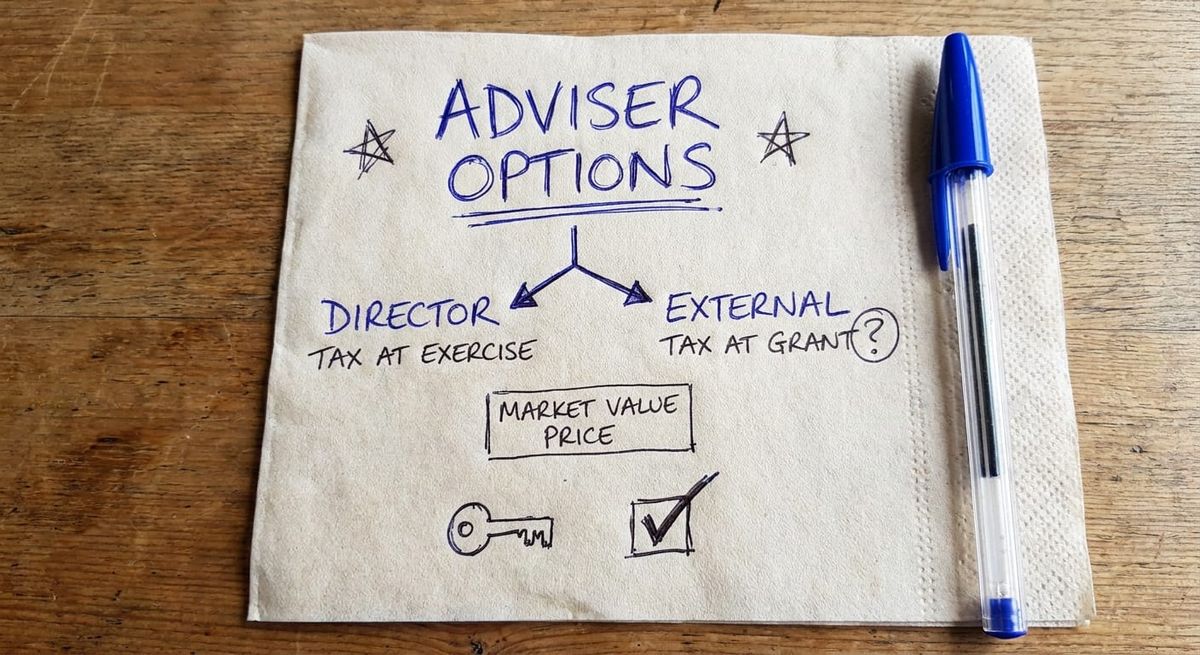
Founders often want to reward an adviser, a consultant or a non-executive with a slice of the company instead of cash. The tax follows the relevant individual's tax status. The same option document can produce a clean outcome for one recipient and a dry tax charge for another. This guide sets out who is inside the rules, how each type of recipient is taxed, how SEIS and EIS interact and what a company should have in place before it signs a grant.
In this guide
- Why can an adviser not hold an EMI option?
- Do the employment-related securities rules apply to an external adviser?
- How is an option taxed if the adviser is an employee or director?
- How is an option taxed if the adviser is genuinely external?
- What about National Insurance, VAT and the company's deduction?
- What happens when the adviser sells the shares?
- How do unapproved options interact with SEIS and EIS?
- What should a company have in place before granting an unapproved option?
- When is a phantom scheme the better route?
- Frequently asked questions
- Where to go from here
Why can an adviser not hold an EMI option?
An EMI option can only be granted to an employee, and the employee must meet a working-time test (broadly 25 hours a week or 75% of working time). An external adviser or consultant fails at the first gate. A non-executive director normally fails the working-time test as well.
That is why unapproved options are commonly deployed. They sit outside the EMI and CSOP codes and are the fallback for people the statutory schemes cannot reach: non-employees, grants above the EMI limits and companies that fail the EMI conditions.
The price of the fallback is tax. An EMI option gives CGT on the whole gain with no National Insurance, and the Business Asset Disposal Relief (BADR) clock runs from the date of grant. For an employee or director an unapproved option gives full income tax on the spread at exercise, and cannot qualify for BADR if exit-only.
Do the employment-related securities rules apply to an external adviser?
Only if the opportunity to acquire the option is available "by reason of an employment" of that person or of anyone else. Employment includes a former or prospective employment.
The following consequences follow.
- A director is inside the rules. The employment income rules apply equally to offices, and the office-holder's employer is the company (s.5 ITEPA 2003). In Vermilion Holdings [2023] UKSC 37 the option was held by a director, and the Supreme Court applied the deeming rule in s.471(3) without enquiry into why the option was granted.
- A genuinely external adviser is outside them. No employment or office means ss.471 and 421B are not engaged. The safeguard is to keep the adviser external: no directorship, no office and no employee-like role.
How is an option taxed if the adviser is an employee or director?
For a recipient inside Part 7 there is no income tax on the grant of an unapproved option, even where the exercise price is below market value ("No liability to income tax arises in respect of the acquisition of an employment-related securities option", s.475(1) ITEPA 2003, text on legislation.gov.uk). The undervalue does not create a grant charge. It enlarges the charge later.
The charge falls on a chargeable event, almost always exercise. The taxable amount is the market value of the shares at exercise, less the exercise price, less any amount paid for the option itself. It is employment income taxed at the holder's marginal rate for the year of exercise.
Vesting is not a tax point for this recipient. Tranches vesting over time change nothing until exercise.
How is an option taxed if the adviser is genuinely external?
The starting position is that the option is non-cash payment for services. The adviser is then taxed under general principles, as trading or miscellaneous income (or corporation tax for a company), on the money's worth of what was received for the work.
The open question is what is received and when? One view is that the option itself is the receipt, valued when it is granted (or as each tranche vests), so a charge can arise before any shares exist. Another is that nothing is taxed until exercise. Neither the legislation nor HMRC's employment-related securities guidance addresses a non-employee option, and the point is unsettled. The charge is on the value of the option, which can exceed the spread because an option has time value, so a low exercise price does not remove it. Take advice on the specific facts before granting.
The practical risk is a 'dry charge'. If the company recently raised at a high valuation and the option has a low exercise price, the adviser may owe income tax on a large value before any shares can be sold.
The main mitigation is to set the exercise price at market value at the date of grant, which lowers the value at grant so that more of the growth falls later. Avoid nil-cost options. Where an adviser would struggle to fund a tax bill with no liquidity, a cash-settled alternative may suit better (see below).
A cautionary note on titles: an advisor who is appointed a director at Companies House moves into the employee regime. Do not give an advisor a board seat for convenience without checking the tax effect first!
What about National Insurance, VAT and the company's deduction?
National Insurance. For a Part 7 recipient the rule is the readily convertible asset test above. For a genuinely external adviser no Part 7 rule applies and the National Insurance position depends on whether the adviser is self-employed or an office-holder in substance. Confirm it before the grant.
VAT. A VAT-registered adviser who takes an option as payment for services makes a supply for non-monetary consideration. Output VAT is due on the monetary value of the option at the tax point (s.19(3) VATA 1994). That is a cash cost to the adviser for a non-cash receipt. The company can usually reclaim the VAT, so the burden is cash flow and not cost.
Corporation tax. When an employee or director exercises, the company generally secures a statutory deduction under CTA 2009 Part 12 Chapter 3 broadly equal to the gain. The relief is keyed to the s.476 chargeable event, which is a Part 7 event. Do not assume it follows to an external advisor. Unlike statutory employee share deductions under Part 12 CTA 2009, a company granting equity-settled options to an external non-employee contractor generally receives no corporation tax deduction for the award or the resulting dilution.
Keep the company's accounting charge separate. The tax relief is computed on the exercise gain and not on the accounting cost at grant.
What happens when the adviser sells the shares?
Employee or director. The CGT base cost is the price paid plus the amount charged to income tax on exercise, so the same value is not taxed twice (s.119A TCGA 1992). A joint s.431(1) election made within 14 days of exercise treats the shares as acquired at unrestricted market value. It costs more income tax up front and moves all later growth into CGT. Private company shares are almost always restricted, so the election matters. There is no automatic s.431A election for an unapproved option.
External adviser. There is no s.431 election because the shares are not employment-related securities. The CGT base cost normally includes the value brought into charge as income for the option plus any price paid, but the exact computation depends on how the option was taxed.
Rates and relief. Gains in 2026/27 are taxed at 18% or 24%. An adviser will often be a higher rate taxpayer and so pay 24%. Business Asset Disposal Relief is rarely available to an external adviser, because it needs a 5% holding and an officer or employee role throughout a two-year qualifying period. For an exit-only unapproved option, the shares are acquired on the eve of the sale. Because the 2-year holding period for BADR begins strictly at exercise (unlike EMI, where the clock runs from grant), an exit-only unapproved option will never qualify for BADR on an immediate exit.
A cut to the BADR lifetime limit was announced at Budget 2026 and is not yet law. See what Budget 2026 means for founders.
How do unapproved options interact with SEIS and EIS?
Two questions arise: the adviser as an investor, and the company's own SEIS or EIS position.
The adviser who also invests.
- Employment bar. Under SEIS neither the investor nor an associate may be an employee in period B, but a director is not treated as an employee (s.257BA ITA 2007). A genuine contractor is not an employee.
- The 30% test can count options. An individual has a substantial interest (SEIS) or is connected with the company (EIS) if they possess or are entitled to acquire more than 30% (s.257BF(1) and s.170(1) ITA 2007). HMRC's manual says an option over existing shares counts, but that a right to require the company to issue unissued share capital is not an entitlement to acquire issued share capital (VCM11080). An option over new shares is therefore not caught on that limb alone, but the assets-on-winding-up limb (s.257BF(2) and s.170(2)) and associates' holdings still need testing if the adviser is close to 30%.
- EIS only: employees and directors. An employee of the issuing company is connected with it, and so is a director who receives payments other than the excluded categories (ss.167 and 168 ITA 2007). A genuine contractor is not an employee, but an adviser who is appointed a paid director can lose EIS relief on their own investment.
- EIS only: existing shareholdings. If an adviser holds shares other than risk finance or qualifying subscriber shares when new EIS shares are issued, relief on the new shares is denied (s.164A ITA 2007). Shares acquired on exercise will not have been covered by a compliance statement unless they were included in one, so they can be "other shares". SEIS has no equivalent.
The company. Grant options over new shares only. If the rules let an option be met by transferring an investor's shares, the investor has granted a call option, which is treated as a disposal and withdraws relief (s.211 for EIS and s.257FC for SEIS). Give no investor anything for consenting to the option pool: that can be value received.
What should a company have in place before granting an unapproved option?
| Item | Why it matters |
|---|---|
| Recipient status recorded (director, office-holder, employee or external) | Decides whether Part 7, s.431 and ERS reporting apply |
| Written valuation at grant | No HMRC agreement is available for unapproved options. Keep a contemporaneous file |
| Exercise price at market value | Keeps the spread at grant small. Avoid nil-cost |
| Vesting separated from exercisability | Exit-only exercise aligns the charge with a sale. See exit-only versus time-based |
| Leaver and lapse terms | Good and bad leaver outcomes for vested and unvested options |
| Authority to grant and pre-emption position | Check the articles and any shareholder consent before the board grants |
| Board approval and a quorate board | A grantee who is a director may be unable to count towards the quorum |
| Option executed as a deed | The adviser pays nothing, so the deed is what binds the company |
| Tax indemnity and, for office-holders, a s.431 election as a condition of exercise | Protects the company and fixes the base cost |
| ERS registration and return if Part 7 applies | Register the "Other" scheme and file by 6 July after the tax year of the first reportable event, including nil returns |
No shares exist at grant, so there is no SH01 and no register of members entry until exercise. An SH01 follows each exercise.
Where Part 7 applies, the penalties are £100 for a late return, rising with delay, and up to £5,000 for a careless inaccuracy (ss.421JC and 421JD ITEPA 2003).
When is a phantom scheme the better route?
A phantom scheme pays the adviser a cash bonus linked to growth in the share price. No shares are issued, so there is no dilution, no new share class and no valuation argument over shares at grant.
For some advisers that is cleaner. It avoids an option that cannot be sold, and it avoids a dry tax charge on an illiquid holding, because the adviser receives cash.
The cost moves to the company. A cash liability arises on the day of the trigger, usually a sale or a funding round, and it must be funded. The adviser also gets no shareholder rights and no CGT treatment on the growth.
Phantom awards suit a short engagement, a modest value and an adviser who wants cash. A real option suits an adviser who is staying and wants to be an owner. Decide between the two before anyone drafts option documents, because the documents, the tax and the cash planning are different for each.
Frequently asked questions
Can a non-executive director hold an EMI option?
Normally not. EMI is for employees who meet the working-time test. A non-executive director is an office-holder, so Part 7 applies, but the realistic routes are an unapproved option or growth shares with an s.431 election.
Is there tax when an adviser is granted an unapproved option?
It depends on status. A director or employee has no charge at grant (s.475(1) ITEPA 2003). A genuinely external adviser is outside Part 7, so the option is treated as payment for services. Whether a charge arises at grant, as the option vests or only at exercise is unsettled, so take advice before the grant.
Does the company have to register an ERS scheme for an external adviser's option?
No, if the adviser is genuinely external, because ERS needs an employment or office connection. If the adviser is or becomes a director, ERS applies. Register the "Other" scheme and file the annual return by 6 July after the tax year of the first reportable event.
Can HMRC agree the value of an unapproved option in advance?
No. The HMRC valuation agreement service covers EMI and the other tax-advantaged schemes, not unapproved options. The company and the holder self-assess the value. Keep a written valuation prepared at the time.
What if the adviser is later appointed a director?
Part 7 reaches former and prospective employment (s.471(2)) and applies equally to offices (s.5 ITEPA 2003), so a grant made in anticipation of an appointment as a director is at risk of being caught. Plan for the director analysis from the start if an appointment is likely.
Can an adviser holding options still invest under SEIS or EIS?
Possibly, but count the options. Options over existing shares count towards the 30% limit, and unissued-share options need testing against the assets limb. Under EIS, shares held on exercise can bar relief on a later subscription (s.164A ITA 2007). SEIS has no equivalent bar.
Should the exercise price be nominal?
Not from a tax efficiency perspective. A nominal or £nil price maximises the taxable spread. Setting the price at market value at the date of grant leaves only later growth to be taxed.
Where to go from here
The right structure depends on who the adviser is, how long they will be involved and what the company has raised. If you are about to grant an option to an adviser, consultant or non-executive, I can check the status, the valuation and the grant documents before anything is signed. You can get in touch to talk it through.
This article is general guidance, not advice for your specific circumstances. The tax treatment of an option depends on the recipient's status, the terms and the date of grant. Take advice before granting an option.